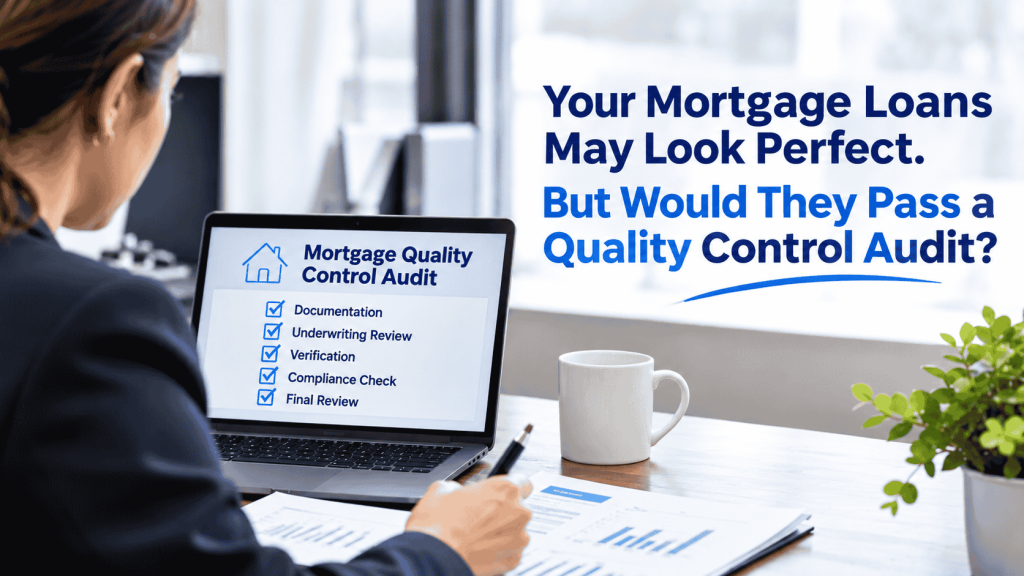
A mortgage loan passes through several stages before it reaches closing and funding. From collecting borrower documents to verifying income, reviewing property value, checking underwriting decisions, and preparing the final loan file, every step matters.
But what happens when a small error goes unnoticed?
A missing document, an incorrect income calculation, or an unsupported underwriting decision can create problems long after a loan has closed. These issues may lead to additional reviews, compliance concerns, unnecessary rework, and potential financial losses.
This is where a mortgage quality control audit becomes important.
For mortgage lenders, wholesale lenders, and third-party origination (TPO) teams, quality control is not simply about finding mistakes. It is about understanding why those mistakes happen, identifying risks, and building a more consistent loan production process.
In this guide, we will explain what a mortgage quality control audit involves, why it matters, which areas lenders should review, and how a structured audit process can support better loan quality and operational efficiency.
What Is a Mortgage Quality Control Audit?
A mortgage quality control audit is an independent evaluation of a lender’s quality control program. It examines whether established procedures are followed, review findings are properly documented, and conclusions are applied consistently.
It is important to understand the difference between a loan quality control review and an audit of the quality control program itself.
Loan QC review: Examines individual mortgage files to identify documentation errors, underwriting weaknesses, eligibility concerns, and other defects.
QC program audit: Evaluates whether the lender’s quality control function follows documented procedures, maintains appropriate records, and applies its conclusions consistently and independently.
For example, a lender may review a sample of closed loans every month. However, if the team does not follow its documented procedures, record findings accurately, or escalate significant issues, the lender may have a weakness in its overall QC program.
A mortgage quality control audit helps identify these process gaps.
Fannie Mae’s Selling Guide provides guidance on lender quality control programs, including documented procedures and independent audits. Lenders should consult the investor requirements that apply to their specific business.
Read Fannie Mae’s lender quality control guidance
Why Is a Mortgage Quality Control Audit Important?
Mortgage lending involves multiple teams, third-party service providers, borrower documents, property information, underwriting decisions, and investor requirements. When these activities are not properly monitored, even small inconsistencies can affect loan quality.
A structured audit helps lenders understand where their processes are working and where improvements are needed.
1. Identify Loan File Errors Early
Not every loan defect is easy to identify during origination. Some issues become visible only when a file receives a detailed review.
For example, a loan may contain income documentation that does not adequately support the underwriting decision. Another file may have inconsistencies between the application, supporting documents, and information recorded in the lender’s system.
A quality control audit can identify whether the lender’s review process detects these issues and whether identified defects are properly addressed.
2. Reduce Compliance and Investor Risk
Mortgage lenders must follow applicable laws, regulations, investor requirements, and contractual obligations. Requirements vary depending on the lender, loan product, investor, and transaction.
A QC audit helps determine whether the lender’s procedures adequately address these obligations. For example, an audit may reveal that certain documents are not consistently verified, findings are not escalated appropriately, or corrective actions are not documented.
Identifying these weaknesses allows management to improve controls before similar issues affect more loans. An audit does not guarantee compliance, but it provides an important way to evaluate whether control processes are functioning as intended.
3. Understand the Root Cause of Recurring Defects
Finding an error is only the first step. The next question is why it happened.
Imagine that multiple loan files contain incomplete income documentation. The immediate response might be to ask the employees responsible to correct the files. However, the underlying problem could be unclear procedures, inadequate training, inconsistent document collection, or a system that does not flag missing information.
A mortgage quality control audit helps identify whether the problem is isolated or connected to a broader process weakness.
4. Improve Operational Efficiency
Repeated reviews, missing documents, unnecessary follow-ups, and incomplete audit records consume valuable staff time.
When lenders understand where errors occur most frequently, they can improve workflows and establish clearer responsibilities.
For instance, if documentation issues repeatedly arise during loan processing, the lender can introduce a consistent checklist or improve the handoff between processing and underwriting.
Over time, better processes can reduce avoidable rework and allow teams to spend more time on complex cases and important decisions.
5. Strengthen Management Oversight
Quality control findings should provide management with more than a list of individual errors. They should help answer practical questions:
- Which types of defects occur most frequently?
- Are defect rates improving or getting worse?
- Are particular loan products or origination channels associated with recurring issues?
- Are corrective actions completed on time?
- Are similar defects appearing after previous remediation efforts?
These insights help management make informed decisions about training, staffing, policies, and process improvements.
What Does a Mortgage Quality Control Audit Review?
The scope of an audit depends on the lender’s business model, risk profile, internal policies, and applicable requirements. However, several areas deserve particular attention.
1. Loan File Documentation
A complete and accurate loan file provides the evidence needed to support lending decisions.
An audit may examine whether required documents are present, information is consistent across the file, and the documentation supports the decisions made.
- Borrower applications and identity information.
- Income and employment documentation.
- Asset and liability information.
- Credit reports and related documentation.
- Property appraisal and collateral information.
- Underwriting conditions and their resolution.
- Closing documents and final loan information.
The objective is not simply to confirm that documents exist. It is to determine whether the documentation supports the transaction and meets the applicable requirements.
2. Underwriting Decisions
Underwriting determines whether a loan meets the lender’s eligibility and risk standards.
A quality control audit can evaluate whether the lender’s review procedures adequately assess the basis for underwriting decisions.
- Was the decision supported by the available documentation?
- Were applicable eligibility requirements followed?
- Were approval conditions properly addressed?
- Were exceptions documented and approved according to policy?
- Were relevant discrepancies investigated?
A well-documented decision is easier to review and explain when questions arise later.
3. Income, Employment, and Asset Verification
Income and asset information play an important role in evaluating a borrower’s ability to repay a mortgage.
An audit may assess whether verification procedures were followed, discrepancies were resolved, and supporting records were maintained.
For example, if the information in an income document differs from the amount used during underwriting, the review should determine whether the discrepancy was appropriately investigated and resolved.
4. Appraisal and Collateral Review
Property valuation is another important area of mortgage quality control.
An audit may examine whether the lender’s procedures appropriately address appraisal documentation, property information, valuation concerns, and collateral risk.
For example, inconsistent property details or an inadequately supported valuation conclusion may require further investigation. Lenders should also review whether appraisal-related concerns are routed to the appropriate personnel and resolved according to established procedures.
5. Third-Party Originations and Vendor Oversight
Wholesale and TPO lenders often work with mortgage brokers, correspondents, appraisers, and other external service providers.
These relationships can increase operational complexity because different parties handle different parts of the loan process.
A QC audit should evaluate whether the lender’s oversight procedures cover relevant third-party activities and whether identified defects are tracked and reported.
For lenders operating across multiple channels, consistent oversight is essential to understanding where risks originate.
6. QC Reporting and Corrective Actions
A quality control process is incomplete if findings are recorded but never acted upon.
An audit should evaluate whether findings are documented, classified according to the lender’s established framework, reported to the appropriate teams, and tracked through resolution.
It should also determine whether recurring problems lead to meaningful corrective actions.
For example, if several files reveal the same documentation weakness, management should be able to determine who owns the corrective action, what needs to change, and how the lender will verify that the change is effective.
How Does the Mortgage Quality Control Audit Process Work?
A structured process makes audits more consistent and helps lenders turn findings into practical improvements.
Step 1: Define the Audit Scope
Begin by identifying which parts of the quality control program will be evaluated. The scope may include prefunding reviews, post-closing reviews, sampling procedures, reporting, vendor oversight, record retention, or corrective action tracking.
Step 2: Review Policies and Procedures
Examine the lender’s written QC plan, operating procedures, reporting standards, and documentation requirements. The objective is to understand what the lender expects its QC team to do and how those expectations are communicated.
Step 3: Examine QC Records
Review selected QC reports, loan review documentation, defect classifications, escalation records, and corrective action plans. Determine whether the records demonstrate that required procedures were followed and conclusions are supported by evidence.
Step 4: Test Consistency and Independence
Check whether similar issues are evaluated consistently and whether QC decisions are made independently of business pressures. The lender should have a reasonable basis for explaining differences in the classification or resolution of comparable defects.
Step 5: Identify Gaps and Root Causes
Document the weaknesses identified during the audit. Separate isolated errors from systemic issues that may affect multiple loans, teams, or origination channels.
Step 6: Develop and Track Corrective Actions
Prepare an action plan that identifies the required changes, responsible owners, expected completion dates, and methods for validating the results. Follow-up reviews should determine whether the corrective actions were implemented and whether the underlying issue has been addressed.
Step 7: Report Results to Management
Present the findings in a clear, structured report. Management should understand the significant issues, their potential impact, recurring trends, and the actions required to strengthen the QC program.
Prefunding QC vs. Post-Closing QC vs. QC Program Audit
These three activities are related, but they serve different purposes.
| Review Type | Purpose |
|---|---|
| Prefunding QC | Identifies selected issues before closing or funding, according to the applicable process. |
| Post-closing QC | Evaluates completed loan files and identifies defects after closing. |
| QC program audit | Evaluates whether the quality control function follows established procedures and applies conclusions consistently. |
A lender should not treat these activities as interchangeable. Prefunding and post-closing reviews evaluate loan quality at different stages, while the QC program audit examines whether the quality control function itself is operating effectively.
Common Challenges in Mortgage Quality Control Audits
Even lenders with established QC programs can encounter operational challenges.
- Inconsistent documentation: Reviewers may document similar findings differently, making trends harder to identify.
- Manual tracking: When reports, findings, and corrective actions are maintained across separate spreadsheets or systems, important updates may be missed.
- Recurring defects: Teams may correct individual files without identifying the process weaknesses behind repeated errors.
- Limited reporting visibility: Management may receive reports without enough detail to understand which issues require immediate attention.
- Third-party oversight gaps: Different origination channels and external providers may create inconsistent documentation and review practices.
- Delayed corrective actions: Findings may remain unresolved when ownership, deadlines, and escalation procedures are unclear.
Addressing these challenges requires clear procedures, consistent documentation, appropriate oversight, and regular evaluation of the QC program.
How Can Mortgage Lenders Make Their QC Audits More Effective?
Improving quality control does not necessarily mean adding more manual reviews. It means making the review process more consistent, risk-focused, and actionable.
1. Standardize Review Checklists
Use documented checklists that reflect applicable requirements and the lender’s internal procedures. Standardization helps reviewers follow the same process and reduces the likelihood of overlooking important review steps.
2. Use Risk-Based Monitoring
Apply the lender’s risk assessment to determine where additional attention may be appropriate. Recurring defects, complex loan products, unusual transactions, or elevated-risk origination channels may warrant targeted review, subject to applicable requirements.
Risk-based monitoring should supplement required random sampling rather than replace mandatory sampling procedures.
3. Track Defects and Corrective Actions
Maintain a clear record of each finding, its severity, its assigned owner, and its resolution status. Reviewing this information regularly helps management identify recurring patterns and determine whether corrective actions are working.
4. Improve Reporting and Data Visibility
Use consistent reporting formats and, where appropriate, centralized tracking tools or dashboards to monitor defect trends, outstanding actions, and review completion.
The objective is to make important information easier to access and act upon, not simply to produce more reports.
5. Evaluate Internal and External QC Support
Some lenders perform QC activities internally, while others outsource certain reviews or use a combination of internal and external resources.
External support may help lenders manage review workloads or access additional operational capacity. However, outsourcing does not remove the lender’s responsibility for maintaining appropriate oversight.
Any external provider should be evaluated for its experience, review methodology, documentation standards, reporting capabilities, data security practices, and ability to meet the lender’s requirements.
How GoSource Can Support Mortgage Operations?
For mortgage lenders, maintaining loan quality involves more than completing individual reviews. Teams also need reliable processes, accurate documentation, consistent follow-ups, and enough operational capacity to keep work moving.
GoSource provides business process outsourcing support for mortgage operations. Depending on the engagement, operational support can help lenders manage defined administrative and documentation workflows, reduce repetitive workload, and improve process consistency.
For lenders evaluating support around their mortgage quality control workflows, the important considerations are straightforward:
- Which administrative or documentation tasks are consuming the most time?
- Where do manual handoffs create delays?
- Are review records and supporting documents organized consistently?
- Can repetitive activities be handled through a standardized process?
- What controls are needed to protect borrower information and maintain accountability?
The right support model depends on the lender’s needs, internal controls, and applicable investor and regulatory requirements.
GoSource’s role is to support agreed-upon operational processes, while the lender retains responsibility for its QC program, review decisions, regulatory obligations, and required oversight.
Learn more about GoSource’s services at GoSource.biz.
Final Thoughts
A mortgage quality control audit is an important part of maintaining a reliable mortgage lending operation. It helps lenders look beyond individual loan defects and evaluate whether their quality control processes are consistent, independent, properly documented, and effective.
The real value comes from acting on the findings. When lenders identify recurring problems, address their root causes, and track corrective actions, they can strengthen loan quality while making their operations more predictable and efficient.
For wholesale lenders, TPO organizations, and mortgage operations teams managing multiple workflows, a structured approach to quality control can provide greater visibility into operational risks and areas for improvement.
Better mortgage quality control starts with finding the gaps, understanding why they exist, and making the process stronger for the next loan.
Frequently Asked Questions About Mortgage Quality Control Audits
1. What is a mortgage quality control audit?
A mortgage quality control audit evaluates whether a lender’s quality control program follows established procedures, maintains accurate records, and applies review findings consistently. It helps identify weaknesses in loan review processes, documentation, reporting, and corrective actions.
2. Why do mortgage lenders need a quality control audit?
Mortgage lenders use quality control audits to identify process gaps, evaluate the effectiveness of their QC programs, and improve oversight. Audits can uncover recurring loan defects, inconsistent review practices, and weaknesses in corrective action procedures before they create larger operational or compliance concerns.
3. What is the difference between a mortgage QC audit and a loan quality control review?
A loan quality control review examines an individual mortgage file for documentation errors, underwriting issues, and other defects. A mortgage quality control audit evaluates whether the lender’s overall QC function follows documented procedures and applies its findings consistently.
4. What does a mortgage quality control audit cover?
A mortgage quality control audit may examine the lender’s written QC plan, loan review records, defect classifications, sampling methodology, reporting practices, vendor oversight, and corrective action tracking. The exact scope depends on the lender’s business model and applicable investor requirements.
5. How often should a mortgage quality control audit be conducted?
Audit frequency depends on applicable investor requirements and the lender’s documented QC program. Lenders should establish an appropriate independent audit process and follow the specific requirements that apply to their organization rather than assume one schedule fits every lender.
6. How can lenders reduce mortgage loan quality control defects?
Lenders can reduce recurring defects by standardizing review checklists, improving documentation practices, identifying the root causes of errors, monitoring defect trends, and tracking corrective actions. Regular training and consistent communication between processing, underwriting, closing, and QC teams can also strengthen loan quality.
7. Can mortgage lenders outsource quality control activities?
Yes. Mortgage lenders may outsource certain quality control activities when permitted by applicable requirements and contractual arrangements. Before choosing a provider, lenders should evaluate its mortgage industry experience, review methodology, reporting capabilities, and data security practices. Outsourcing does not eliminate the lender’s responsibility for appropriate oversight.
8. How can a mortgage quality control audit improve operational efficiency?
A mortgage quality control audit can reveal repetitive errors, inefficient handoffs, inconsistent documentation, and gaps in corrective action tracking. Addressing these issues can reduce avoidable rework, improve reporting visibility, and help mortgage operations teams use their time more effectively. Operational support from providers like GoSource may also help manage defined administrative workflows, depending on the lender’s needs.